UK Moves to End Apple Pay's iPhone Monopoly
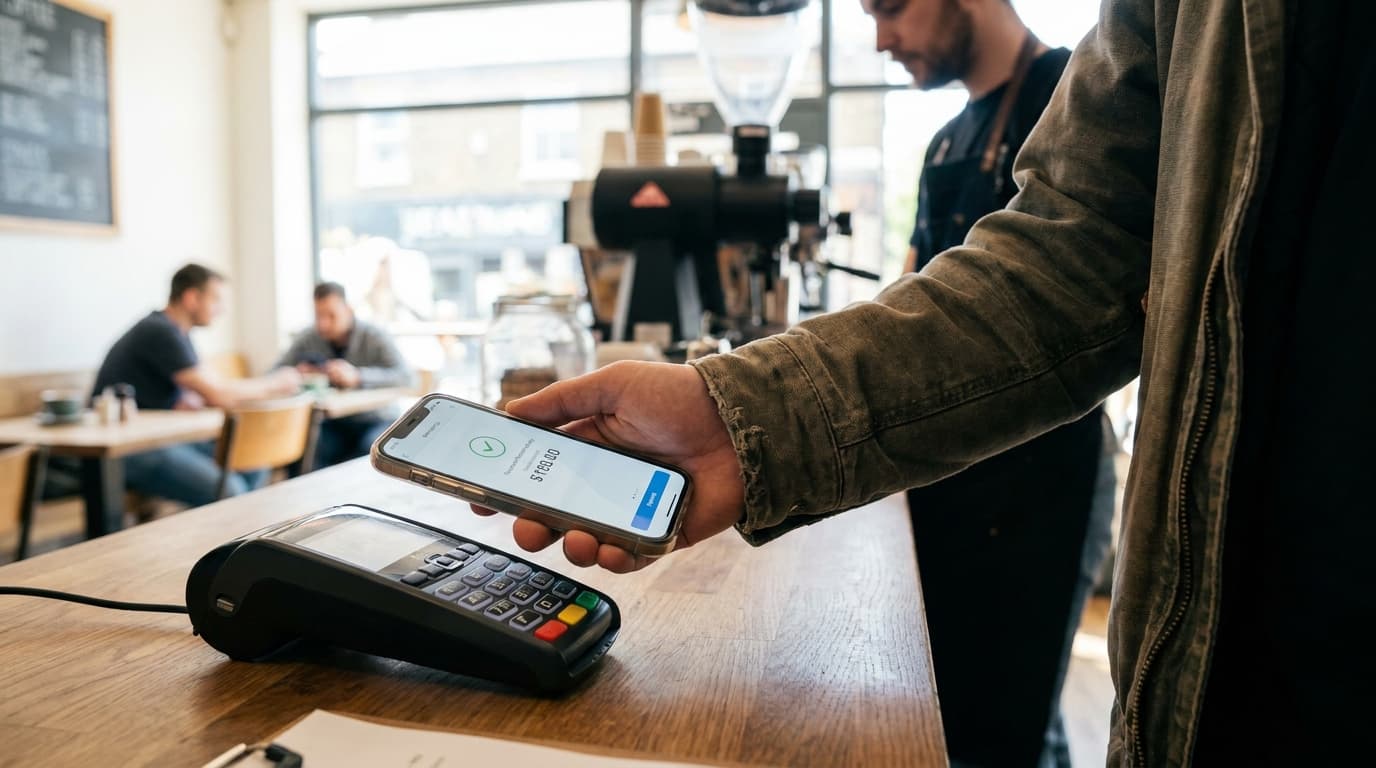
TL;DR: UK regulators are forcing Apple to open the iPhone's NFC chip to rival payment services. This move could end Apple Pay's exclusive control over tap-to-pay, creating new opportunities for banks and fintech companies.
Key facts
- Category
- Tech Updates
- Impact
- Critical
- Published
- Source
- ComputerWorld
Full summary
UK regulators want to force Apple to open the iPhone's tap-to-pay chip, ending Apple Pay's exclusive control on iOS devices.
The United Kingdom is taking formal steps to dismantle Apple's exclusive control over contactless payments on the iPhone. According to reporting from ComputerWorld, the UK's Competition and Markets Authority (CMA) has proposed new rules that would force Apple to grant competitors access to the Near-Field Communication (NFC) technology embedded in its devices. For over a decade, this NFC chip, which enables tap-to-pay functionality, has been reserved exclusively for Apple Pay. The regulator’s proposal, now open for consultation, aims to inject much-needed competition into the mobile payments market. If enacted, the decision would allow banks and financial technology companies to offer their own tap-to-pay solutions directly from their iOS apps, fundamentally altering the payment landscape for millions of iPhone users in the UK.
The core of this change lies in the hardware and software that facilitate contactless transactions. NFC is a short-range wireless technology that allows two devices to communicate when brought close together, making it ideal for secure payments. On iPhones, Apple has historically maintained a tight grip, restricting direct access to the NFC controller for payment purposes. While third-party apps could use NFC for non-payment functions like reading information tags, they were barred from emulating a payment card to transact at a terminal. The CMA's proposed mandate would require Apple to create and provide developers with Application Programming Interfaces (APIs) that open up this capability. This would allow a user to potentially set a default payment app other than Apple Wallet and use their preferred bank's app for tap-to-pay, creating a more seamless and integrated experience within that financial ecosystem. This technical shift represents a significant change in iOS architecture, one that demands a careful balance between openness and security.
This action by the UK's CMA is not an isolated event but part of a broader global trend of regulatory pushback against the dominance of Big Tech. It closely mirrors similar initiatives in the European Union, where the Digital Markets Act (DMA) has already compelled Apple to make significant changes to its business practices, including opening up its platform to alternative app stores. For years, financial institutions and fintech startups have argued that Apple's exclusive control over the iPhone's NFC chip stifles innovation and gives its own payment service an unfair competitive advantage. Regulators now appear to be siding with this view, prioritizing market competition and consumer choice over a single corporation's control of its hardware platform. The move is a clear signal that governments are becoming more assertive in their efforts to level the playing field in digital markets and prevent platform owners from leveraging their dominance in one area to limit competition in another.
For founders and developers, this development is a major strategic opening. It creates the potential to build new payment solutions on iOS that can compete directly with Apple Pay on features, user experience, and even transaction fees. This could unlock new revenue streams and allow for deeper integration of payment services with existing banking and loyalty apps. For CTOs, IT leaders, and security teams, the focus will shift to managing the new landscape of opportunities and risks. The primary concern will be the security of third-party access to sensitive hardware. Teams will need to closely monitor Apple's technical documentation for the new APIs to understand the security model and assess potential vulnerabilities. The immediate next step is the conclusion of the CMA's consultation period, which will be followed by a final ruling. The industry will be watching closely to see the specifics of Apple's compliance plan and how it will implement these foundational changes to its mobile operating system.
Why it matters
For developers and engineers, this regulatory action unlocks direct access to the iPhone's NFC hardware for the first time. It creates a new frontier for building innovative payment solutions outside of Apple's ecosystem, but also introduces complex security and integration challenges for managing third-party access to sensitive hardware.
Business impact
This move directly challenges Apple's services revenue and control over the iOS payment ecosystem. For fintechs and banks, it creates a major opportunity to compete with Apple Pay on features and fees, potentially lowering transaction costs. However, it also introduces new compliance and security risks for businesses.
Tags
Related on Notifire
Related stories
Primary source: ComputerWorld